

BondbloX analysis by Appwee
I approached BondbloX as a finance app for a very specific kind of shared decision: two people in the same household want to discuss bonds, compare information, or monitor an investment idea without treating a shared phone as a shared financial identity. That distinction matters. A bond-trading tool can be useful on a family tablet or a partner’s phone, but the device is only the meeting point; the account, suitability decision, and responsibility still belong to the individual user.
BondbloX comes from BondbloX Pte. Ltd. and focuses on bond trading, market information, and analytics rather than everyday banking. It is free to install, although in-app items are listed from $21.99 to $59.99 each. The app is marked for Everyone, runs on Android 8.0 or later, and its current version is 6.70. Those details make it relatively easy to try on an older household device, but they should not be confused with a promise that every person in a home will find the service appropriate for their financial situation.
How BondbloX fits into shared household use
The most realistic household scenario is not handing the app to a child and asking them to manage money. It is a couple reviewing a bond idea after dinner, or an adult child helping a parent understand what they are seeing on screen. One person may already follow fixed-income markets while the other wants a clearer explanation of maturity, yield, issuer risk, or the difference between holding a bond and trading it. In that setting, the analytics are more useful as a conversation starter than as an automatic decision-maker.
I would use it with one person operating the device and the other asking questions. That keeps the discussion focused and avoids the common mistake of assuming that a visible quote or chart is a recommendation. A bond can look attractive because of its income, yet still carry risks connected with the issuer, liquidity, currency, maturity, or the price paid. An app can organize information; it cannot make those household trade-offs disappear.
The shared-device angle also exposes an important boundary. If a partner opens the app on your phone, that does not make the partner an account holder, authorized trader, or owner of the money involved. I would avoid leaving a financial session open on a family tablet, especially where other people can browse the device. The safest routine is simple: use the app together when needed, finish the discussion, and make sure the person whose account it is remains the one making and confirming any consequential action.
That may sound obvious, but finance apps are different from shared entertainment apps. A family member can pass around a streaming profile without much consequence. A bond platform involves personal decisions and potentially meaningful amounts of money. BondbloX works best in a household when everyone treats the screen as a place to review information, not as a communal wallet.
What the app is good at during a household discussion
The strongest use case is structured comparison. Instead of asking, “Which bond is best?”, I would begin with a narrower question: “Which characteristics matter to us?” A household might care about predictable income, a particular maturity range, a currency they understand, or the ability to hold an investment without needing to sell quickly. BondbloX’s emphasis on bond trading and analytics suits that process better than a basic banking app that only shows balances.
A useful workflow is to write down the decision criteria before browsing. One person can keep the conversation practical while the other examines the available information. This reduces the temptation to chase the most eye-catching yield. It also makes disagreements clearer: perhaps one person values income while the other is more concerned about issuer quality or the time commitment. The app becomes a shared research surface rather than a source of impulse.
Another non-obvious benefit is that a household can separate research from execution. I would first review candidates together, note the questions that remain, and only later decide whether an action is appropriate. That pause is valuable because the excitement of discovering a potentially attractive bond can otherwise turn into a rushed purchase. BondbloX is more helpful when it supports a repeatable process than when it is used for quick guesses.
Still, I would not assume that every important detail can be understood from a single screen. Bond analytics often need context: whether a figure refers to a current market price, an indicative value, a yield under particular assumptions, or information that may change. When discussing the app with someone less experienced, I would read labels carefully and explain what each number means before comparing it with another instrument.
Setting boundaries before anyone else uses the device
BondbloX is free to install, which lowers the barrier to trying it, but “free” does not mean that the financial activity around it is risk-free. The listed in-app purchase range also means I would not let a child or an inexperienced household member explore payment prompts casually. If the device is shared, the person responsible for the account should control purchases and review what is being selected before anything is confirmed.
I would also establish a clear rule about credentials. A partner may help read a screen, but that does not require sharing a password, verification code, or private account information. If someone needs regular access, the correct arrangement is the one supported by the relevant financial service and the account owner’s legal responsibilities, not an improvised shared login. BondbloX should not be treated like a family calendar where everyone uses the same sign-in.
For a parent helping an adult child, the boundary is especially important. Guidance can include explaining terms, checking arithmetic, or asking whether the investment matches the stated goal. It should not quietly become a transaction performed on someone else’s behalf. I prefer a two-step arrangement: the helper explains what is visible, and the account owner independently reviews and confirms the final decision.
On a shared Android device, I would keep notifications and recent screens in mind as well. Even without inventing any special privacy feature, ordinary device habits matter. Lock the phone, avoid saving sensitive details where other users can see them, and do not leave the app open while a child is playing on the same tablet. These are sensible precautions for any finance application, but they matter more when several people use one screen.
Coordinating decisions without turning the app into a family account
Household coordination works best when responsibilities are written down in plain language. One person may gather information, another may challenge the assumptions, and the account owner may make the final decision. That arrangement prevents the familiar problem where everyone believes someone else checked the maturity, costs, or risk.
I would keep a short external note after each discussion: the purpose of the investment, the expected holding period, the main concern, and the question that still needs an answer. This is not a feature claim about BondbloX; it is a practical companion habit. Analytics are easier to use when the household remembers why a candidate was considered in the first place. It also helps prevent a later screen review from becoming a completely new decision based only on whatever looks interesting that day.
For couples, this approach can reduce friction. A person who is comfortable with markets may move quickly through technical information, while the other person may need time to ask basic questions. Rather than treating that difference as a weakness, I would use it as a check against overconfidence. The less experienced participant should be able to explain the investment in their own words before the household commits money.
There is a trade-off here. A shared review process takes longer than opening a conventional bank app and looking at a balance. That extra effort is justified only when the household actually wants bond-specific research. If the goal is simply to see savings, transfer money, or track ordinary spending, BondbloX is the wrong tool. Its value comes from its narrower focus, not from replacing a general-purpose financial app.
Age, trust, and the Everyone label
The Everyone content rating describes the app’s general suitability as software, not a child’s readiness to make investment decisions. I would be comfortable showing an older teenager how bond terminology works in an educational conversation, but I would not interpret the age label as permission to let a minor trade or access an adult’s account. Financial maturity, legal authority, and supervision are separate questions.
For younger users, the best exercise is hypothetical. Discuss why a bond might pay income, why prices can change, and why a higher return can come with greater uncertainty. Use the app as something to observe with an adult present, not as a game or a shortcut to making money. The moment real credentials or payment choices enter the picture, the household should return control to the authorized adult.
Trust also matters between adults. A shared phone can create accidental visibility into balances, watchlists, or activity, and a family relationship does not automatically remove the need for privacy. I would ask before opening another person’s session, even if the device belongs to the household. That small courtesy is more important than any convenience gained by treating every account as communal.
BondbloX’s average rating is 3.6 from around two hundred ratings, with a smaller body of written feedback. I read that as a reason to test the app personally rather than assuming it will suit everyone. A rating in that range suggests a mixed experience, and finance tools are particularly sensitive to differences in expectations: an experienced bond user may want depth, while a beginner may find the terminology demanding. The best way to judge the fit is to see whether the interface helps your household ask better questions.
Where it stands beside more familiar finance apps
Compared with a bank application, BondbloX is more specialized. A bank app usually wins for balances, transfers, card activity, and basic account management. BondbloX makes more sense when the household has moved beyond “How much money do we have?” and is asking “How should we evaluate a bond opportunity?” Choosing between them is not a matter of one being universally better; they solve different problems.
Compared with a broad investing app, its bond-centered identity may be an advantage for someone who wants to focus on fixed income instead of scrolling through shares, funds, and digital assets. The trade-off is that a broader platform may provide a more complete view of a mixed portfolio or make it easier to handle several asset classes in one place. If the household wants one dashboard for everything, a general investment service may be more convenient.
Compared with spreadsheets, BondbloX should be easier for discovering and reviewing bond information, while a spreadsheet remains better for recording household goals, comparing scenarios, and tracking decisions over time. I would use both if the investment is important: the app for current research and a simple private record for the reasoning behind the decision. That combination reduces dependence on memory and helps expose when a promising yield does not match the household’s time horizon.
Compared with professional research terminals, the app is likely to feel more approachable and practical for an individual user, but a household should not confuse a mobile interface with institutional-level analysis. The right question is whether the information is sufficient for the decision being considered. For a small exploratory allocation, the app may be a useful starting point; for a complicated or highly concentrated position, independent research and qualified advice deserve a place in the process.
Friction I noticed in the decision process
The largest limitation is not necessarily a missing button; it is the learning curve created by the subject itself. Bonds have terms that can sound similar while describing different risks. If someone opens BondbloX expecting a simple “buy or avoid” answer, the experience may feel less friendly than a basic savings app. I would not recommend it to a person who has no interest in learning what the numbers represent.
There is also the danger of false precision. A clean figure can make a decision feel objective even when the underlying assumptions deserve scrutiny. In a household review, I would ask whether the displayed information is current, what costs may apply, how easily the position could be sold, and what happens if the issuer’s circumstances change. Those questions are not optional decorations around the analytics; they are part of using them responsibly.
The app’s free installation is convenient, but the presence of paid in-app items means I would review the purchase path carefully before involving another family member. I would also avoid allowing a shared device to become the only place where the household stores its financial understanding. Keep important records in an appropriate private location and make sure the account owner knows how to manage their own access.
Finally, a mobile screen encourages short sessions. That is useful for checking a question, but not always ideal for a full investment review. I prefer to use BondbloX after defining the purpose of the session, rather than browsing indefinitely. A timed review with a written checklist is less exciting, but it is more likely to produce a decision that reflects the household’s goals instead of the app’s most noticeable information.
Who should install it, and who should skip it
I would recommend trying BondbloX to an adult who is specifically interested in bonds, wants market information and analytics in a dedicated app, and is willing to verify details before acting. It can also suit a couple or family member who wants to learn together, provided the account and execution boundaries remain clear. The Android compatibility is broad enough for people using older supported devices, and the free download makes an initial evaluation straightforward.
I would skip it if your main need is budgeting, bill payment, card management, or a simple savings overview. I would also skip it as a first step for a child, a person looking for guaranteed returns, or anyone who expects the app to replace personal research. A general investment app may be better for a diversified portfolio, while a bank app is more appropriate for routine household money.
Before committing to any financial action, I would ask myself three practical questions: Do I understand the bond’s purpose in my plan? Can I explain the main risk to another person? Would I still be comfortable if I could not sell at the moment I wanted? If the answer to any of these is no, more research is needed, regardless of how polished the screen looks.
My household verdict
BondbloX is a focused finance app rather than a family money-management hub. I like the idea of using its bond trading and analytics emphasis to support a calm, informed conversation between adults. Its best contribution is helping a household move from vague interest in bonds to specific questions about goals, time horizon, and risk.
At the same time, the app should not blur account ownership or turn a shared phone into a shared financial identity. The Everyone rating makes the software broadly approachable, but it does not make investment decisions suitable for every age. Keep credentials private, supervise younger users, and let the authorized account holder remain responsible for any action.
My final view is measured: BondbloX is worth exploring if bonds are genuinely the subject you want to understand. It is less convincing as an all-purpose finance app, and it is not a substitute for careful research or household communication. Used as a dedicated research tool, with a checklist and clear boundaries, it can earn a place in an adult investor’s routine. Used casually by whoever happens to pick up the family tablet, it creates more confusion than convenience.
Gallery
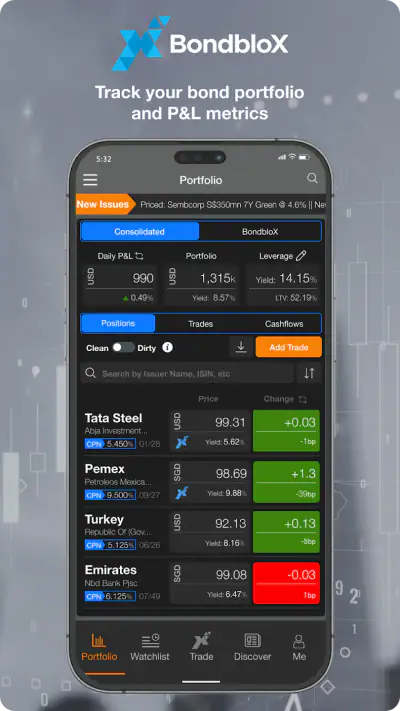
BondbloX Pros and Cons
- Supports fractional bond investing with lower entry amounts.
- Offers access to bonds from multiple markets and issuers.
- Provides portfolio tracking and investment overview tools.
- Can help diversify beyond traditional stocks and funds.
- Displays bond details to support more informed decisions.
- Bond availability may vary by country and investor eligibility.
- Fixed-income investments still carry issuer and market risks.
- Some bonds may have limited liquidity before maturity.
- Fees
- spreads
- or currency costs can reduce overall returns.
- The app may feel complex for users new to bond investing.
BondbloX Frequently Asked Questions
What is BondbloX and how does it work?
BondbloX is a digital investment platform focused on fractionalized bonds, allowing eligible users to access smaller portions of selected fixed-income securities rather than purchasing an entire bond. After creating an account and completing verification, users can browse available offerings, review maturity, coupon, currency, and risk information, then place an order subject to availability and platform rules.
Is BondbloX suitable for beginners in investing?
BondbloX may be easier to approach than traditional bond markets because fractional ownership can reduce the amount needed to start. However, it is not risk-free or automatically suitable for every beginner. New investors should understand bond pricing, interest-rate movements, issuer default risk, liquidity limitations, fees, and currency exposure before investing, and should read each offering’s documentation carefully.
What are the main risks of investing through BondbloX?
Investing through BondbloX still involves the normal risks associated with bonds and digital investment platforms. The issuer may fail to make payments, bond prices can fall when interest rates rise, and some instruments may be difficult to sell before maturity. Currency fluctuations, market conditions, platform availability, and differences in investor protection may also affect the final result.
How much money do I need to start using BondbloX?
The minimum investment depends on the specific bond offering and the fractional units made available on the platform. One of the service’s key advantages is that fractionalization may make certain bonds accessible with less capital than a conventional full-bond purchase. Before committing funds, check the current minimum order, applicable fees, payment requirements, and any account restrictions.
Can I sell my BondbloX investment whenever I want?
You should not assume that every BondbloX investment can be sold instantly. The ability to exit may depend on whether a secondary market or matching facility is available for that particular bond, as well as demand from other investors, trading hours, and platform conditions. If no buyer is available, you may need to hold the investment until maturity, where applicable.














